Chapter 15 · Companion tool
The Beginner Investing Roadmap
Four principles: diversification, low fees, long horizon, automatic contribution. Four vehicles, added over years, never all at once. Two layers: security and growth.
If there is a match, capture exactly all of it. It is compensation you already earned. Beyond the match, the employer plan is usually not the best home for the next dollar, until the IRA is full.
The default home for early retirement dollars. Pay today’s known tax rates now, withdraw tax-free later. Broad index funds inside, bought automatically. The Roth has income limits, and the IRS resets them almost every year. For 2026, what you can put in starts to shrink at $153,000 of modified adjusted gross income for a single filer or head of household, and at $242,000 for a married couple filing jointly, and it reaches zero at $168,000 and $252,000. Check the current year at irs.gov before you fund it.
Any self-employment income can open one, if the business has no employees other than you and a spouse. Higher limits, Roth and traditional flavors. Already in a 401(k) at a day job? The employee part of the limit is shared between the two plans. Worth a conversation with a CPA before you open one.
After the match is captured, the IRA is full, and you have gone back to the employer plan for more. Broad, boring, low-cost index funds. VOO, VTI, FXAIX, SWPPX and their peers.
Two layers
Security. The safety net from Chapter 11: the first month of expenses in savings at your own bank, the rest in high-yield savings at an online bank. The layer that does not move when everything else does.
Growth. Broad-market index funds inside the employer plan to the match, the Roth IRA, a solo 401(k) if you qualify, and the taxable account once the others are full. The layer that builds the number on your Destination Card.
Four more exist and they are real: a self-directed IRA, physical metals, REITs, and the HSA used as a retirement account. Each is a second decision about the same dollar. They are in Appendix B at the back of the book, and none of them is needed to build the number.
The fee audit (Appendix A, Day 26)
Every fund you own, in every account, including the old plan from a job you left. The expense ratio is on the fund’s page inside the portal, under fees, details or fund facts. This page remembers what you type.
Before you buy anything, check the expense ratio. Above roughly 20 basis points, ask exactly what you are paying for. Boring wins, quietly, decade after decade.
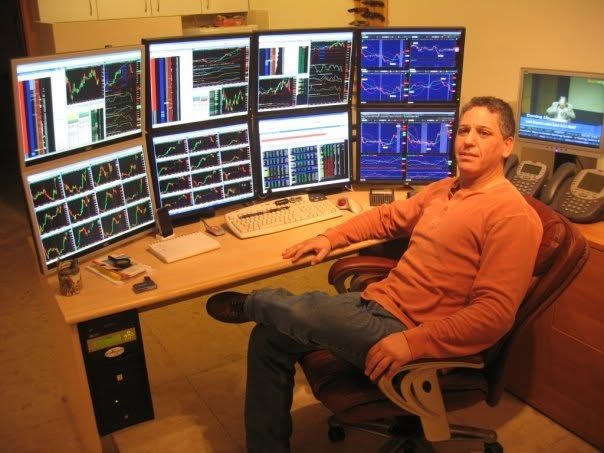
That is my desk, not a stock photograph. It is also why the book says day trading is a job, not an investment. If you want that job, commit to it the way you would commit to becoming a surgeon or a pilot. Do not try it in the evenings after your day job.
Where to actually do this
Every link below goes to a government agency, a regulator, or the one free credit report site federal law authorizes. None of them pay me anything, and none of them will quietly become a different company next year. That is the whole reason they are the links on this page.
- investor.gov Securities and Exchange Commission · the compound interest calculator, and a plain-English explanation of every vehicle on this roadmap
- ssa.gov/myaccount Social Security Administration · your real benefit estimate, from your real earnings record, not a guess
- irs.gov/retirement-plans Internal Revenue Service · this year’s contribution limits and Roth IRA income limits, from the only source that sets them
- treasurydirect.gov U.S. Treasury · buy Treasury bills and I bonds directly, with no middleman and no fee
- brokercheck.finra.org FINRA · look up any advisor or firm, free, before you hand over a dollar
- annualcreditreport.com The federally authorized source for your free reports from all three credit bureaus. Type the address yourself; look-alike sites are common
What opening the account actually looks like
The reason most people never open the account is not the money. It is not knowing what the screen is going to ask. So here is the screen, in advance. Fifteen minutes, once.
1. Who you are. Legal name, date of birth, address, Social Security number, and your employer. Standard, and required by law for every brokerage in the country.
2. What kind of account. A Roth IRA, a traditional IRA, or a plain taxable brokerage account. Chapter 15 in the book tells you which one, and in what order.
3. How it gets funded. Your bank routing and account number, and the amount. Set the recurring transfer here, on day one, before you have the chance to negotiate with yourself.
4. Who gets it if you do not. The beneficiary. On most account types it overrides your will. Most people skip it. Do not be most people.
5. What you actually buy. Money sitting in the account is not invested. This is the step people miss. Choose the fund, check the expense ratio, place the order.
Where people actually open it
Three large, low-cost providers do this well for beginners. Any of the three is a defensible answer, and the difference between them matters far less than whether you open one at all this month.
- investor.vanguard.com Vanguard · founded by Jack Bogle, who built the first index fund an ordinary person could buy; home of VOO and VTI
- fidelity.com Fidelity · home of FXAIX, one of the index funds Chapter 15 names
- schwab.com Charles Schwab · home of SWPPX, one of the index funds Chapter 15 names
I receive nothing from any of them. No affiliate link, no referral fee, no relationship. If that ever changes I will say so on this page.
Keep the streak going
Finish the chapter in the book, then come back for the next tool. If something here did not land, bring it to Open Mic and I will walk through it live.